Resources
Insurance claims
How to make a claim, step by step
A claim usually starts on a bad day. Something is damaged or gone, and the paperwork arrives while you are still dealing with it. One thing to know upfront: Kapi Insurance arranges your cover, and you claim directly with your insurer. The steps below are the ones that get a claim paid.
The process runs about the same whether you're claiming on car, home or contents insurance.
What should you do immediately after an incident?
Make sure everyone is safe, photograph the damage, report a theft or a crash, then ring your insurer. Four steps, in that order. The first few hours decide how smoothly the claim runs.
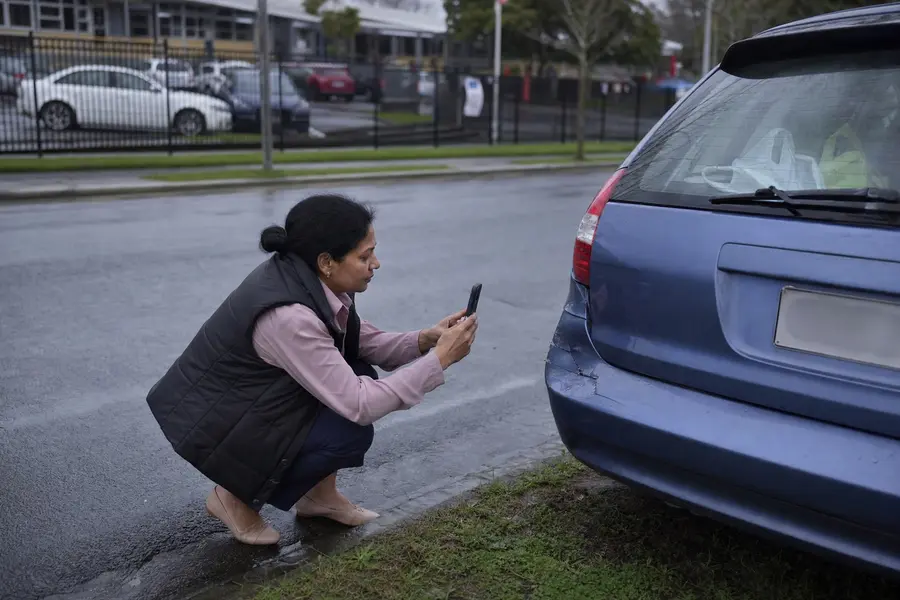
Photos taken at the scene carry more weight than anything written later.
-
Make sure everyone is safe
If anyone is hurt, call 111. If there is a risk of more damage, a burst pipe or exposed wiring, do what you reasonably can to stop it getting worse.
-
Document the damage
Grab your phone. Photos and video from several angles, every room, every damaged item. Thin evidence at this stage is what slows a claim down or turns it into an argument. Keep the damaged items until the insurer says you can bin them. They may want to look.
-
Report it to the right people
Car accident? Swap details with the other driver and file a police report if one is needed. Theft or break-in? Report it to police straight away and get a file number, because the insurer will want it. Storm damage? Write down the date, the conditions and any weather warnings in force at the time.
-
Contact your insurer
Ring your insurer as soon as you can. Most policies require prompt notification, and a delay hands them a reason to push back. Have the policy number ready and describe what happened in plain terms.
Paperwork
What documents do you need for an insurance claim?
You need your policy number, the date and time of the incident, photos of the damage, proof of ownership, and an estimate of the cost. Theft and break-in claims also need a police file number. Gather what you can before you lodge.
For all claims
- - Your policy number and claim reference (if already lodged)
- - Date and time of the incident
- - Description of what happened
- - Photos or video of the damage
- - Receipts, invoices, or other documents proving ownership and value
- - Police file number (required for theft and break-in claims)
- - An estimate of the total cost, including repairs or replacement
For car accident claims
- - Other driver's name and contact details
- - Other vehicle's registration number
- - Other driver's insurance details
- - Names and contact details of witnesses
- - Location of the car accident
- - Photos of all vehicles involved and the scene
- - Written repair quotes (if available)
Lodgement to Settlement
What happens after you lodge an insurance claim?
The insurer receives the claim, assigns an assessor, and decides the payout. You pay the excess and they cover the rest. The assessor stage is where most of the waiting sits.
-
Ring the insurer's claims team or lodge through their online portal. Either channel works.
-
Send the claim form with the supporting documents: receipts, photos, the police file number if there is one, and any repair quotes.
-
An assessor is assigned. They read the file, inspect the damage if needed, and work out what the insurer will pay.
-
If you disagree with the decision, dispute it through the insurer's complaints process, or take it to the IFSO for an independent ruling.
-
At settlement you pay the excess and the insurer covers the rest: repairs, a replacement, or a cash payout up to your limits.
Keep It Moving
How do you keep an insurance claim moving?
Report it promptly, answer questions once and in writing, keep a copy of everything, and chase the assessor. Small omissions early in the process are what stretch a claim into weeks.
- Report your claim promptly
- Most policies require notice as soon as reasonably possible. Waiting hands the insurer a reason to push back. Once you lodge, the Fair Insurance Code requires ICNZ member insurers to acknowledge the claim within 5 business days and decide it within 10 business days of having everything they need.
- Be honest and thorough
- Exaggerating or leaving something out can void the claim. Describe what you saw, include the detail you have, and let the evidence carry it.
- Keep records of everything
- Save the emails. Screenshot the texts. Keep copies of the forms and write down who you spoke to and when. If a dispute starts later, that paper trail is your side of the story.
- Don't accept the first offer if it seems low
- If the number looks low, say so. The Fair Insurance Code from the Insurance Council of New Zealand sets the standards every member insurer must meet. Use the internal complaints process first, then the Insurance and Financial Services Ombudsman (IFSO) if it stalls.
- Prevent further damage
- Take reasonable steps to stop things getting worse. Tarp a damaged roof after a storm. Turn the water off at the mains if a pipe lets go. Keep the receipts for emergency repairs, because those costs usually form part of the claim.
- Check your claim status regularly
- Get a reference number on the first call, then check in weekly. If repairs are involved, ask for a timeline. Claims stall quietly when nobody is chasing.
Is a small claim worth making?
A small claim is worth making when the loss clearly beats your excess, and often not worth it when the two are close. Worked example: a $500 excess against an $800 repair leaves $300. Get the repair quote first. Plenty of damage that looked serious comes in under the excess once it is priced.
The excess is only half of it. Insurers price on claims history, so a paid claim follows you into future renewals, and application forms ask about past claims whichever insurer you approach next. That is an argument for thinking about a borderline claim. It is not an argument for sitting on a real loss.
Insurance earns its keep on the losses you could not absorb: the house fire, the burglary that empties the flat, the $30,000 liability bill. Below that line, run the numbers.
If you withdraw a claim, is it still recorded?
Yes. Lodging a claim creates a record, and withdrawing it later does not erase that record. Most of New Zealand's general insurers, covering roughly 95 percent of the market, share claims data through the Insurance Claims Register, where claims stay for ten years. The record exists from the moment you lodge.
It shows up at application time. When a new insurer asks about claims you have made, a lodged-then-withdrawn claim belongs in the answer. Accurate answers protect the new policy. Non-disclosure is one of the standard reasons a claim gets declined.
If you are only ringing to ask a what-if question, say that at the start, and ask how the call will be recorded before a claim number is opened.
The Dispute Path
What can you do if your claim is declined?
You can ask for the decision in writing, use the insurer's internal complaints process, then take the complaint to an independent dispute resolution scheme. The schemes are free for consumers. Here is how each step runs.
-
Ask for the decision in writing
Get the decline letter and the clause the insurer is relying on. A phone explanation is hard to argue with. A written decision names the wording, and the wording is what a dispute turns on.
-
Use the insurer's internal complaints process
Under the Fair Insurance Code, the insurer must acknowledge your complaint within 5 business days, respond within 10 business days of having all the information, and update you at least every 20 business days. The Code allows the internal process up to two months to resolve it.
-
Take it to the ombudsman scheme
If the complaint is unresolved after two months, or reaches deadlock, escalate it to the insurer's dispute resolution scheme, usually the Insurance and Financial Services Ombudsman (IFSO) or FSCL. Both are free for consumers. The IFSO Scheme can investigate complaints up to $500,000 plus GST, and you generally have three months from the deadlock letter to refer yours.
What about faulty insurance repairs?
If your insurer arranged and paid the repairer and the work is not right, go back to the insurer first and use the complaints path above if it stalls. If you chose the repairer and the insurer cash-settled, your remedy sits with the repairer under the Consumer Guarantees Act, which requires services to be carried out with reasonable care and skill.
Kapi Insurance is a member of the Insurance and Financial Services Ombudsman Scheme (5008525), so an independent process covers complaints about our own service too. We arrange the cover and you claim directly with your insurer. If a claim decision has you stuck, we can help you read the wording you are arguing about.
Get your cover sorted before you need it
We will check your current cover and flag the gaps before you need to claim on it.